

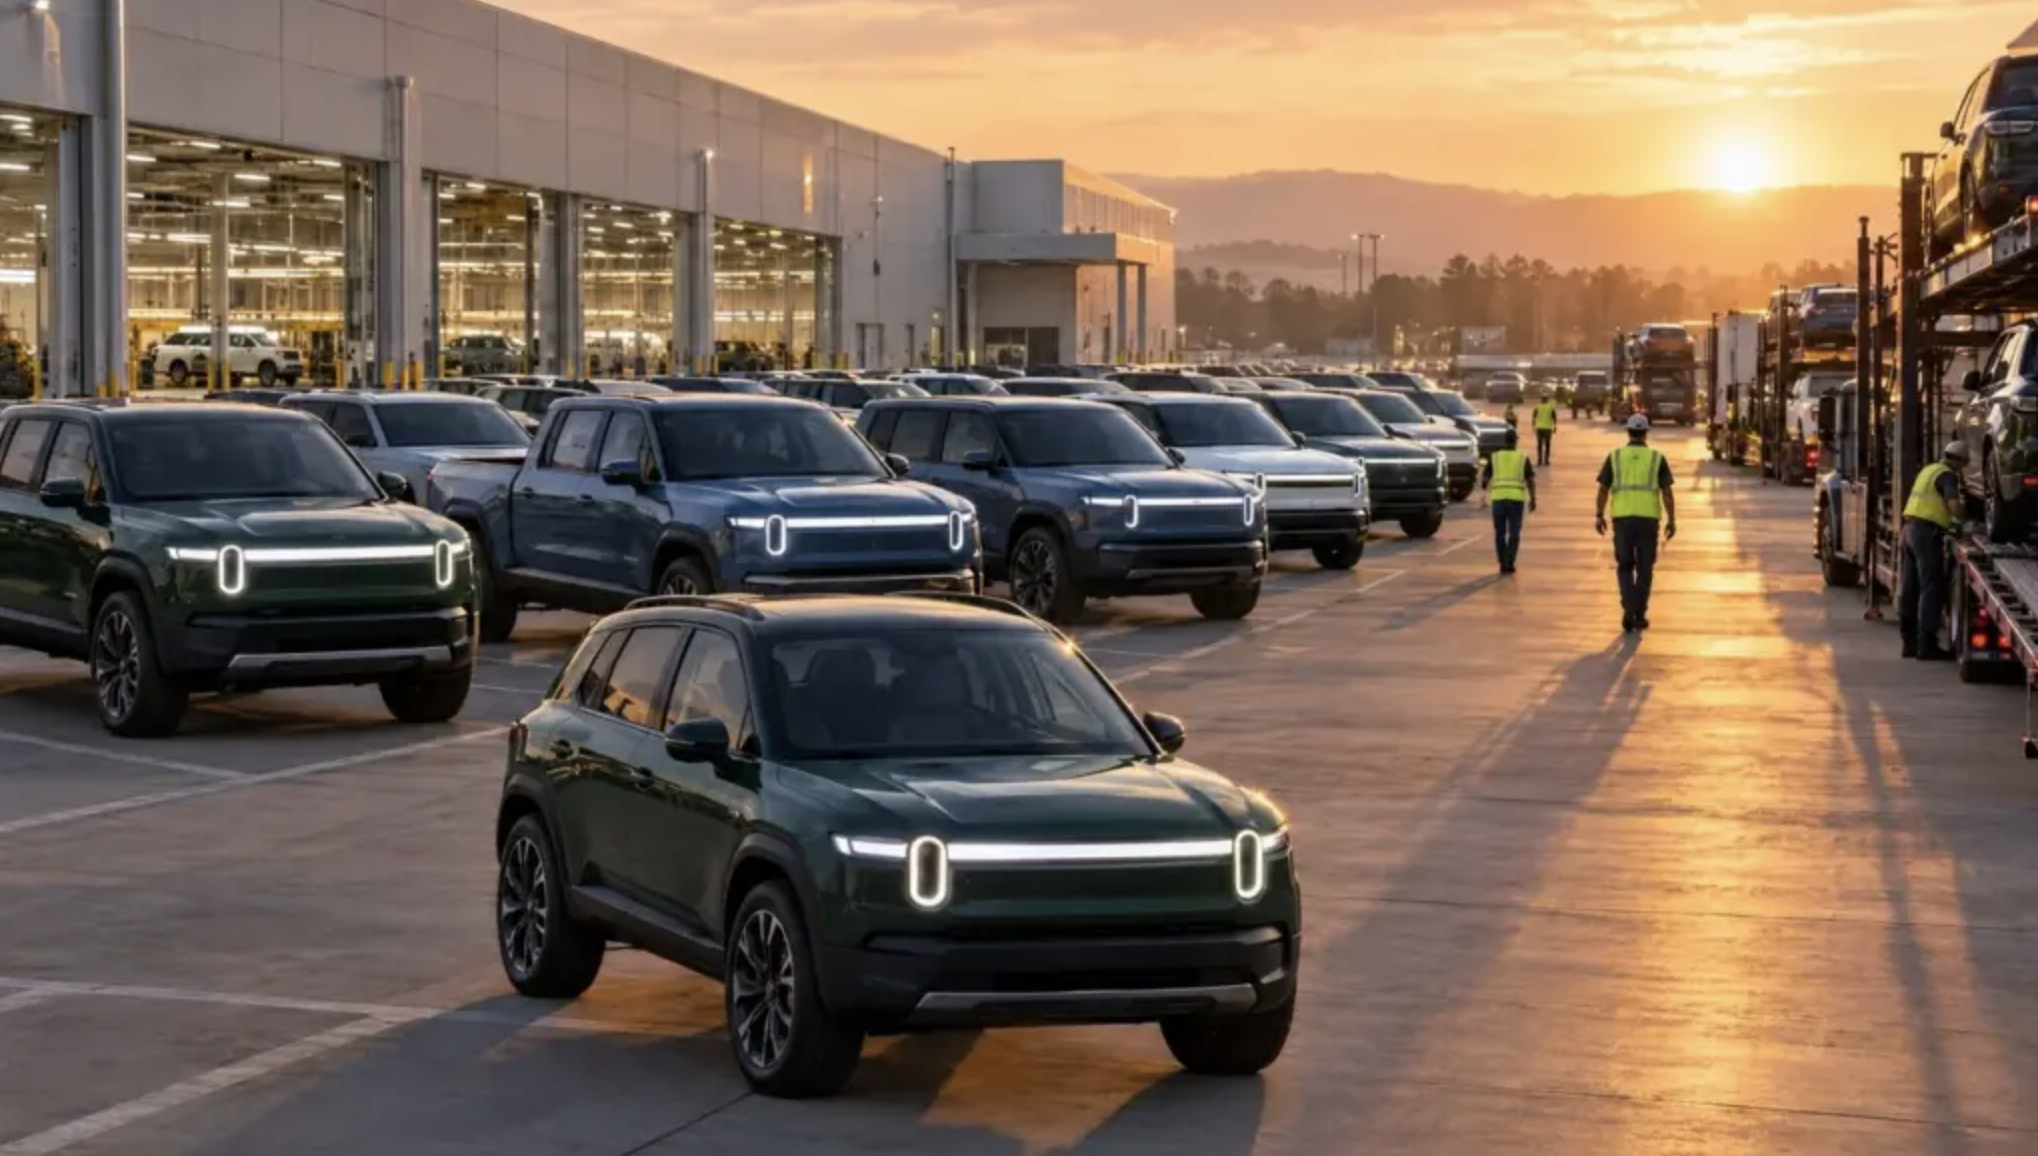
Rivian has reported its latest quarterly numbers, and the Rivian third-quarter 2026 results landed better than analysts had penciled in. Revenue grew 38 percent, the loss per share was smaller than expected, and the company nudged up how many vehicles it expects to deliver this year.
In this article, we will explore the headline figures, what the new R2 SUV changed, how the guidance moved, why an Uber payment is tied to a year-end milestone, and how to read the report without getting carried away.
The Headline Numbers in Rivian Third Quarter 2026 Results
According to a Stocktwits roundup updated on October 30, 2026, Rivian posted third-quarter revenue of $2.16 billion, a rise of 38 percent from the same quarter a year earlier. Analysts had been looking for roughly $1.99 billion, so the company cleared the consensus bar. On the earnings side, the adjusted loss came in at $0.48 per share, against an expected loss of about $0.56.
Those two facts answer the question most readers bring to an earnings story: was it a good quarter or a bad one? Measured against expectations, it was a good one. Revenue was higher than forecast, the loss was narrower than forecast, and management raised the low end of its delivery outlook. Whether that is enough to change how you think about the company depends on what you care about, and the rest of this piece tries to separate the confirmed numbers from the interpretation.
A word on sourcing before going further. The figures in this article come from a single secondary roundup rather than from the company’s own shareholder letter or its regulatory filing. Roundups of this kind are usually accurate on the headline numbers, but they sometimes compress details, so anyone making a decision should check the primary documents. The company publishes them on its investor relations pages, and the filing is available through the US Securities and Exchange Commission.
Nothing here is investment advice. This is an explainer about what the report said and what it means for the business, not a view on any share price.
Simple Arithmetic on the Revenue Figure
A 38 percent rise to $2.16 billion implies that revenue in the same quarter last year was roughly $1.57 billion. That is simple arithmetic on the two numbers in the roundup, not a figure the roundup itself states, and it is rounded. The gap between the reported $2.16 billion and the $1.99 billion consensus is about $170 million, again simple arithmetic.
For a company that has spent years burning cash while it scales, a revenue beat of that size is welcome but not decisive. The more informative question is what kind of revenue it was, and that depends heavily on the vehicle that arrived in the middle of this year.
Revenue and Loss Beat Expectations, but a Loss Is Still a Loss
An adjusted loss of $0.48 per share is better than the $0.56 analysts expected, but it remains a loss. That sentence sounds obvious, and yet it gets lost in the cheerful phrasing that often follows an earnings beat. A smaller loss than forecast is progress in the direction every electric vehicle startup needs, which is to say, toward a point where each vehicle sold covers its share of the costs of building and running the company.
Adjusted figures deserve a little caution. Companies choose which items to leave out when they calculate adjusted numbers, commonly including stock-based pay and certain one-off charges. That does not make the adjusted figure wrong. It does mean that two companies’ adjusted losses are not directly comparable, and that the adjusted number can look rosier than the loss measured under standard accounting rules.
What Analysts Mean by Consensus
The consensus figure is an average of estimates from analysts who follow the company. It is a useful yardstick for how a result will be received on the day, because markets react to the surprise relative to expectations rather than to the absolute number. A company can grow quickly and still disappoint if analysts expected faster growth, and the reverse is also true.
The consensus is not a measure of how well the business is run. It reflects what a group of forecasters thought would happen, using information the company supplied through earlier guidance. When a company raises guidance, as Rivian did here, it also moves the target for the next round of estimates.
How to Weigh a Beat of This Size
A useful habit is to look at the beat as a share of the total. The revenue surprise of about $170 million is roughly 8.5 percent of the $1.99 billion consensus, which is simple arithmetic on the roundup’s numbers. That is a clear beat rather than a rounding difference, and revenue beats of this scale usually mean volume or pricing came in above the model, not that a single sale shifted between quarters.
On the loss side, the gap between $0.48 and $0.56 is $0.08 per share, also simple arithmetic. Because the figures are per share, they depend on the share count, and they cannot be turned into a dollar loss without that number, which the roundup does not provide.
Why a Beat Does Not Settle the Bigger Question
A revenue beat tells you demand and deliveries were at least as strong as modeled for one quarter. It does not tell you whether the company can earn a profit at scale, how much cash it will need, or whether the next product line will sell as well as the first. Those are the questions that decide the long game, and they are addressed more by the guidance changes and by the cost picture than by the quarter’s top line.
R2 Deliveries Explain the Raised Outlook
The roundup credits the R2, Rivian’s smaller and more affordable SUV, as the reason the company lifted its delivery guidance. Deliveries of the R2 began in June, so the third quarter was the first full quarter in which the new model could contribute. The company also expects R2 to account for the majority of its deliveries in the fourth quarter, which tells you how quickly the sales mix is shifting.
That shift matters for a practical reason. Until this year, Rivian’s consumer lineup consisted of the R1T pickup and the R1S SUV, both of which sit at higher price points. A model aimed at a wider audience can reach far more buyers, and a factory that builds more of one model at a steady pace usually learns to build it more efficiently as the months pass.
A Second Shift at the Illinois Plant
To build more R2 vehicles, the company added a second shift at its Illinois plant, according to the roundup. A second shift is a straightforward way to raise output without building new space: the same assembly line runs for more hours with a second crew. It also commits the company to higher labor costs and to selling what it builds, so it is a sign of confidence in demand rather than only a sign of capacity.
Adding shifts is faster than adding factories, but it has limits. Equipment needs maintenance windows, suppliers must deliver parts for the higher volume, and new hires need training. Early in a model’s life those frictions can cap output below what the schedule suggests, which is one reason the guidance range is still wide.
Why Timing of a Launch Matters for the Year
Because the R2 reached customers in June, its impact on the full-year total is limited to roughly the second half. Each additional month of volume production therefore counts for more than it would in a mature model, and small changes in the weekly build rate move the annual total. That helps explain why management felt able to raise only the floor of the range: the remaining months are well enough mapped to rule out the weakest outcomes, but not so well mapped that the top of the range can safely move.
Shoppers sometimes assume a company with a new model is limited only by demand. In the first months, supply is usually the tighter constraint, with parts availability and training setting the pace. The addition of a second shift suggests the company believes it can sell more than a single shift can produce.
What a New Model Does to the Numbers
A new model launch tends to pull in two directions at once. Sales rise because there is a new product to sell, but costs also rise because early production is less efficient, and because the company is paying to ramp suppliers and train workers. A quarter that shows both rising revenue and a smaller loss than expected suggests the ramp is going at least as smoothly as analysts feared it might.
It is wise to avoid reading too much into one quarter of a ramp. The fourth quarter will be the first in which R2 is expected to dominate the mix, and that will show whether the economics of the smaller vehicle work as hoped.
Guidance Changes Line by Line
Guidance is the company’s own forecast for the rest of the year, and it often moves markets more than the quarter that just ended. The roundup lists three changes: a higher delivery range, a narrower expected adjusted core loss, and a lower capital spending range. The table below sets them out, followed by notes on how to read each.
| Item | Previous guidance | New guidance | Direction |
| 2026 deliveries | 65,000 to 70,000 vehicles | 67,000 to 70,000 vehicles | Low end raised |
| Adjusted core loss | Earlier range (not given in the roundup) | Narrowed by $100 million at the midpoint | Check the filing |
| Capital expenditure | Earlier range (not given in the roundup) | $1.4 billion to $1.5 billion | Lowered |
Deliveries
The top of the delivery range did not change at 70,000. The bottom moved from 65,000 to 67,000. By simple arithmetic, the midpoint of the range therefore rises from 67,500 to 68,500, an increase of 1,000 vehicles. That is a modest lift, and it is mostly a statement that the worst-case scenario has become less likely rather than that the best case has improved.
Raising only the floor is a common and cautious way to update guidance. It tells you management has more visibility on the year, since one more quarter of results is in hand and the order book for the final months is clearer. It stops short of promising more than the company is sure it can deliver.
Adjusted Core Loss
The roundup says the adjusted core loss guidance was narrowed by $100 million at the midpoint. The excerpt available does not give the underlying range, so the exact before-and-after figures should be taken from the company’s own release. Narrowing a loss outlook generally signals that management has a tighter view of costs, and a shift in the midpoint indicates that the central expectation moved, which is the part to read closely in the filing.
Capital Spending
Capital expenditure guidance was lowered to between $1.4 billion and $1.5 billion. Lower spending means less cash leaving the company for equipment, tooling and buildings. The roundup does not say why the range came down, and there are several ordinary explanations: projects shifting in timing, purchases costing less than planned, or spending being deferred. Without the company’s explanation, it is best to treat the reason as unexplained.
The midpoint of the new range is $1.45 billion, which is simple arithmetic on the roundup’s two numbers.
Cash, Capital Spending and Why Narrower Losses Matter
Readers who do not follow finance daily often ask why a company with rising sales still talks so much about losses and spending. The answer is that building cars is one of the most capital-hungry businesses there is. Factories, tooling, battery supply and software all cost money long before the first customer pays, and the company has to fund that gap until each vehicle sold covers its share.
Operating Loss Versus Capital Spending
These are two different drains on cash. The operating loss is the shortfall between what the business earns and what it costs to run, including materials, wages, research and warranty. Capital expenditure is money spent on durable assets, such as production lines, that will be used for years. A company can cut one without the other, and the roundup reports movement in both: a narrowed adjusted core loss outlook and a lowered capital spending range.
Both moves point toward less cash going out the door than before, but neither says how much cash remains. That figure sits in the balance sheet, and it is the number that tells you how much runway the company has. The roundup does not provide it, so it is worth looking up in the filing.
Why Scale Changes the Economics
Fixed costs, such as the salaries of engineers and the expense of running a factory, do not shrink when fewer cars are built. When output rises, those costs are spread across more vehicles, which lowers the cost per car. That is why a higher delivery count tends to narrow losses even if each car sells for the same price. The pattern in this report, higher deliveries together with a tighter loss outlook, fits that logic, although the roundup does not break the effect down.
There is a counterweight. A cheaper model usually carries a thinner margin, so if the mix tilts toward R2 the revenue per vehicle may fall even as volume rises. Revenue growth of 38 percent in a quarter in which R2 deliveries were only starting is therefore worth watching in the fourth quarter, when the mix is expected to shift further.
Reading Cost Discipline From the Guidance
A lower capital spending range can signal cost discipline, or it can signal that projects have slipped. Both readings are plausible, and the numbers alone cannot separate them. If the company discusses the change on its earnings call, the explanation will usually be found there, and transcripts are often posted on the investor relations page.
A practical rule is to look for the reason behind each guidance change before drawing a conclusion. A reason stated in the company’s own words beats any outside interpretation, including this one.
Uber’s Conditional Investment and the Year-End Autonomy Test
One detail in the roundup deserves more attention than it usually gets. A $250 million tranche of Uber’s planned investment in Rivian depends on an autonomy milestone due by year-end. In other words, part of the money is not unconditional. It is tied to technical progress on self-driving capability, and the deadline is close.
The roundup does not describe the milestone itself, and this article will not guess at it. What can be said is how conditional investments of this kind generally work. An investor commits capital in stages and releases each stage when the company reaches an agreed target. That protects the investor if the technology is late, and it gives the company a reason to stay on schedule.
Why the Structure Matters to Readers
For someone following the company, the structure turns a vague promise into a date. If the milestone is met, the $250 million tranche becomes available, and the company will probably say so. If it is missed or delayed, the tranche may be pushed back or renegotiated, and the company would be expected to disclose that too.
Such outcomes are not predictions here, and it would be a mistake to treat the milestone as either easy or hard on the evidence available. The useful habit is simply to note the date and look for the company’s own statement around the turn of the year.
Autonomy and the Wider Industry
Self-driving ambitions are common across the car industry, and partners that run large ride-hailing networks have an obvious interest in them. For a vehicle maker, a partner like that offers both money and a potential customer base. For the partner, the arrangement offers early access to vehicles and software designed with their needs in mind. Both sides carry risk, because autonomy has repeatedly taken longer than first announced across the industry.
Risks and Open Questions the Report Does Not Settle
Good quarters can hide unfinished business. Several questions remain open after this report, and a careful reader will keep them in view.
Can the R2 Ramp Keep Its Pace?
The raise in delivery guidance rests heavily on a model that has been on sale only since June. If its production rate, quality or demand falls short of the plan, the fourth-quarter outlook will be the first place it shows. The range of 67,000 to 70,000 vehicles for the full year is narrow, which leaves little room for a shortfall without a further guidance change.
Will Losses Keep Narrowing?
An adjusted loss of $0.48 per share is smaller than the expected $0.56, and the loss outlook was narrowed. Yet a company that is still losing money each quarter has to fund that gap from its cash reserves or from new capital. The roundup does not give the cash position, so this article cannot comment on how long the existing resources would last.
Is the Evidence Strong Enough?
This article relies on one secondary source, and that is a real limitation. Headline figures from roundups tend to match the company release, but details such as how a guidance change was described can be altered by summarizing. If the narrowing of the loss outlook or the capital spending range matters to you, read the primary document.
Policy and Market Conditions
Electric vehicle demand is affected by interest rates, by consumer confidence, by charging availability and by government incentives, and the rules on incentives can change. The roundup says nothing about these matters, so this article does not either. Readers should check current rules before assuming any particular buyer incentive applies to a purchase.
A Checklist for Following Rivian From Here
If you want to follow the story without being swept along by headlines, a short routine helps. The list below is built around the facts in this report and can be adapted to any company that reports quarterly.
| Step | What to check | Why it helps |
| 1 | The company’s own shareholder letter | Confirms the headline figures in the roundup |
| 2 | The fourth-quarter share of R2 in deliveries | Tests the claim that R2 will be the majority |
| 3 | The year-end autonomy milestone | Determines whether the $250 million tranche is released |
| 4 | Capital spending against the $1.4 billion to $1.5 billion range | Shows whether cost discipline is holding |
| 5 | Full-year deliveries against 67,000 to 70,000 | The simplest scorecard for the year |
For Owners and Prospective Buyers
If you are thinking of buying an R2 or any other Rivian vehicle, the quarterly report is a poor guide to your own experience. Look at reviews, test drive the model, ask about delivery times, and check the warranty terms and service locations near you. Production ramps can cause delays, so confirm the delivery estimate in writing.
For General Readers
If you follow the company for news rather than for a purchase, the three items to circle on the calendar are the next earnings release, the year-end autonomy milestone and the full-year delivery tally. Each will either confirm or complicate the story told by this report.
Conclusion
The third quarter gave Rivian a better set of numbers than analysts expected, and the R2 is the main reason. Revenue of $2.16 billion, a smaller adjusted loss and a higher floor for deliveries are all verified in the roundup, but they come from a single secondary source and should be checked against the company’s filing.
The harder questions are still ahead: whether R2 volume holds, whether the loss keeps shrinking, and whether the Uber milestone is met by the end of the year. For now, the sensible stance is to treat the quarter as encouraging evidence, not a verdict.
Frequently Asked Questions
How Much Revenue Did Rivian Report in the Third Quarter of 2026?
According to a roundup updated on October 30, 2026, revenue was $2.16 billion, up 38 percent from a year earlier. Analysts had expected roughly $1.99 billion.
Did Rivian Beat Earnings Estimates?
On the loss measure, yes. The adjusted loss was $0.48 per share, compared with an expected loss of about $0.56.
How Many Vehicles Does Rivian Expect to Deliver in 2026?
The company now guides to between 67,000 and 70,000 vehicles, up from a range of 65,000 to 70,000. The change raised the low end only.
When Did R2 Deliveries Begin?
Deliveries of the R2 SUV started in June, based on the roundup. The company expects R2 to make up the majority of fourth-quarter deliveries.
Is Uber Investing in Rivian?
The roundup refers to a planned Uber investment, with a $250 million tranche that depends on an autonomy milestone due by year-end. Details of the milestone were not given, so check the company’s statements.
Should I Buy Rivian Stock After These Results?
This article cannot say, because it offers no investment advice. A licensed financial professional can discuss your own situation, and the company’s filings are the best place to start your research.